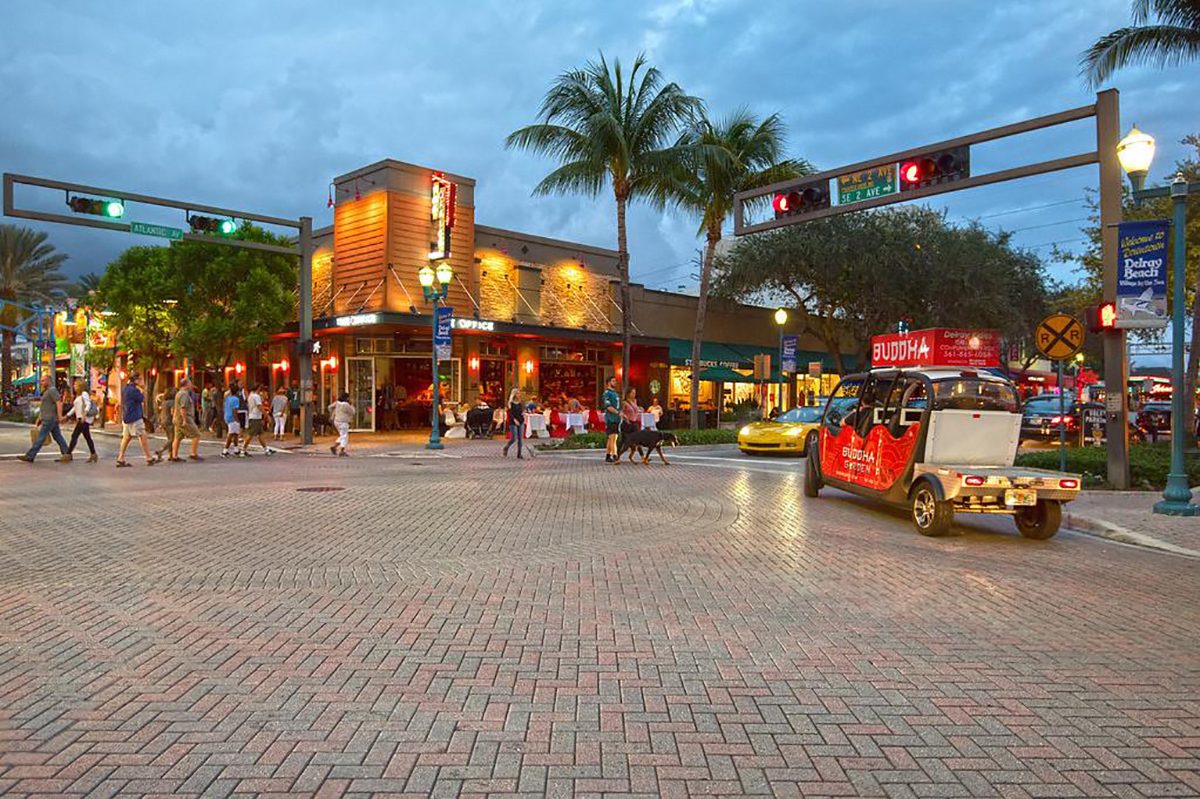
First-Time Buyer's Guide to Deerfield Beach, Florida (2026): Budgets, Loans, and Starter Neighborhoods
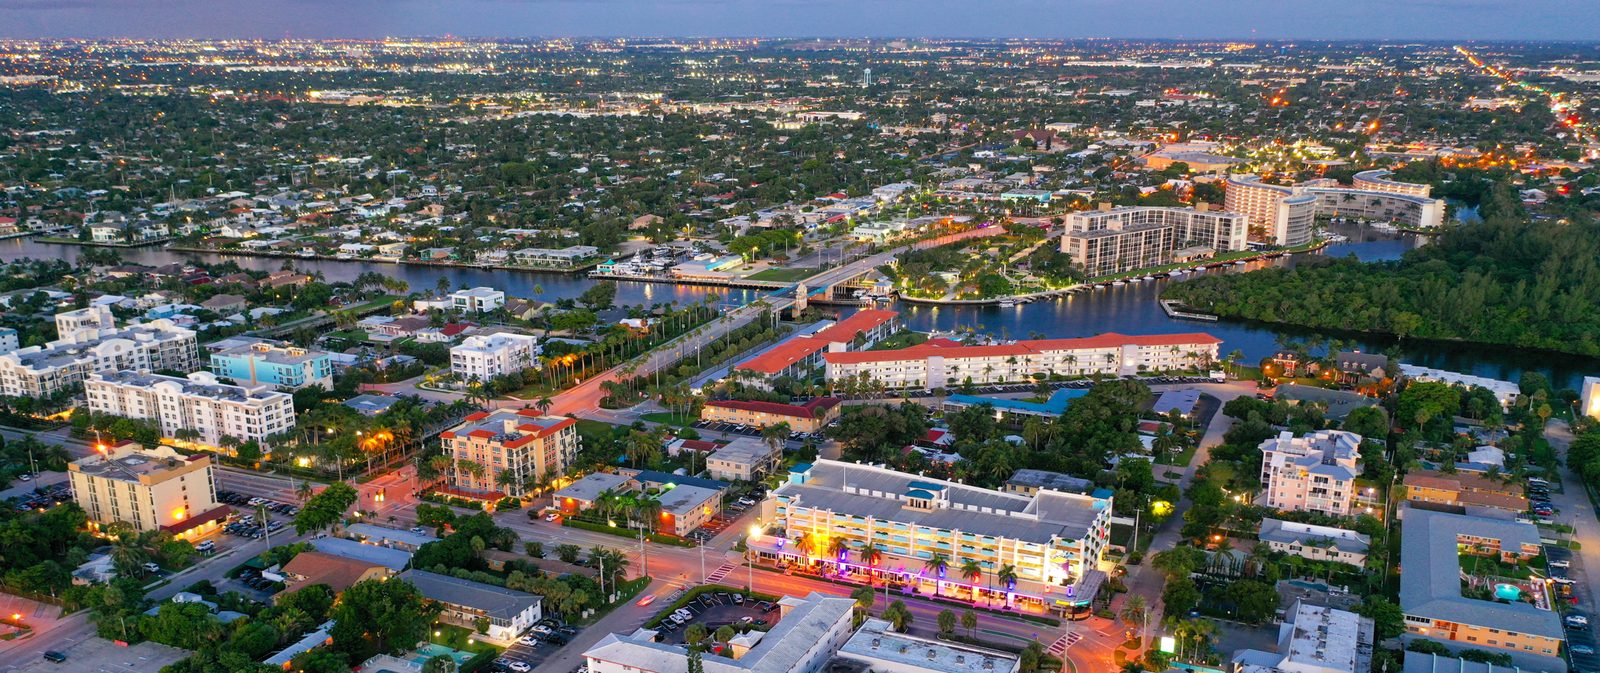
First Time Buyer Deerfield Beach: What $340K to $480K Actually Buys You in 2026
If you’re searching “first time buyer Deerfield Beach,” here’s the honest answer up front: you’re looking at roughly $340,000 to $480,000 for a realistic starter home in 2026, depending on whether you buy a condo, a townhome, or a single-family house, and depending on how close you want to be to the sand. You can do this with as little as 3 to 3.5 percent down using an FHA or conventional loan, and there’s real down payment assistance available if you qualify. What most people don’t tell you is that the hard part isn’t the loan. It’s picking the right pocket of Deerfield Beach for your budget and your life stage. Let’s get into it.
Where Deerfield Beach Actually Sits
Deerfield Beach is part of the Fort Lauderdale metro, tucked into the far northeast corner of Broward County right up against the Palm Beach County line. Hillsboro Boulevard is the border. Cross it north and you’re in Boca Raton pricing. Stay south and west and you’re still in Broward, with Broward’s tax rates and (usually) Broward’s more approachable price tags.
The city runs from the Atlantic Ocean on the east to the Sawgrass Expressway corridor on the west, which means “Deerfield Beach” covers two very different buying experiences. East of Federal Highway (US-1), you’re paying beach-adjacent prices. West of I-95, especially out toward Powerline Road and the Coconut Creek line, you’re in more typical Broward suburban territory, and that’s where most first-time buyers actually land.
That east-west split is the single most important thing to understand before you start touring homes. A buyer who says “I want to live in Deerfield Beach” without specifying which side of I-95 they mean is really describing two different budgets. East of US-1, you’re competing with retirees, second-home buyers, and cash buyers from up north who don’t blink at asking price. West of I-95, you’re competing mostly with other working families, and that’s a very different negotiation.
Commute-wise, Deerfield Beach gives you I-95, the Florida Turnpike, and Tri-Rail (there’s a Deerfield Beach Tri-Rail station) for getting down to Fort Lauderdale or up to Boca and West Palm. It’s a legitimate commuter town for anyone working in either direction, which is part of why it holds value. It’s also why inventory here doesn’t sit long once it’s priced right. A well-priced townhome under $400,000 in Century Park or Waterways typically gets multiple showings in the first week, so if you’re serious, being pre-approved before you tour matters more here than in slower-moving inland markets.
What You Can Actually Afford: Realistic Budgets by Home Type
Break it down by what you’re actually buying, because “average home price” numbers get thrown around without context and they don’t help you plan.
Condos: Older 1-2 bedroom condos in complexes like Century Village (age-restricted, 55+, so not for most first-time buyers) start well under $150,000, but those aren’t available to younger buyers. Non-age-restricted condos and low-rise units in areas like Deer Creek or along Hillsboro Boulevard run more realistically from $180,000 to $300,000 for a 2-bedroom, depending on age, HOA fees, and whether the building has completed its structural reserve requirements under Florida’s post-Surfside condo safety law. Expect a wide range even within the same complex. A 2-bedroom unit on a lower floor with an outdated kitchen might list at $185,000, while a renovated unit two floors up in the same building lists at $265,000. The HOA fee doesn’t change much between those two units, so factor that fixed cost into your monthly number regardless of which one you choose.
Townhomes: This is the sweet spot for a lot of first-time buyers. Expect $330,000 to $430,000 for a 2-3 bedroom townhome in communities like Waterways or Century Park, with HOA dues that cover exterior maintenance, roof, and often a community pool. Most of these run $300 to $450 a month in HOA fees, which sounds like a lot until you price out a new roof or exterior paint job on a single-family home yourself. For a buyer who wants predictable monthly costs and doesn’t want a Saturday-morning to-do list, that math works in the townhome’s favor.
Single-family homes: Older single-family stock in Cresthaven, Kendall Green, or the neighborhoods around Quiet Waters Park typically runs $420,000 to $550,000 for a 3-bedroom, depending on lot size, age, and whether it’s been updated. Waterfront and canal-access homes in The Cove push well past that, often into the $700,000s and up, which is a different buyer entirely. Homes built in the 1970s and 1980s in these neighborhoods often need a roof, AC system, or plumbing update within the first few years of ownership if the seller hasn’t already done it, so a lower purchase price doesn’t always mean a lower total cost of ownership. Ask for the age of the roof and AC before you fall in love with a house, not after your inspection comes back.
Those numbers move with the market, so treat them as a planning range, not a quote. But they tell you something important: Deerfield Beach still has entry points under $350,000, which is increasingly rare this close to the ocean in Broward County.
A Realistic First-Time Buyer Scenario
Here’s how this plays out for an actual buyer. Say you’re a dual-income household making a combined $95,000 a year, with $12,000 saved and decent credit around 660. That’s a common profile for a first-time buyer in this market, and it’s worth walking through because it shows how the pieces fit together.
With an FHA loan at 3.5 percent down, $12,000 gets you into a home priced around $340,000, once you account for closing costs eating into your cash. That puts you in range for a townhome in Century Park or an older single-family home in Kendall Green, but likely prices you out of Waterways or anything east of US-1. If you qualify for Florida Hometown Heroes on top of that FHA loan, that same $12,000 stretches further because the program can cover a chunk of your closing costs and down payment, freeing up your own cash for reserves or moving expenses.
Now say that same household stacks a Broward County SHIP deferred second mortgage on top of the first. Depending on income tier, that can knock your out-of-pocket cash down to close to nothing beyond an earnest money deposit. That’s the difference between “we can’t afford Deerfield Beach” and “we closed on a townhome six months ago.” Most buyers never run these numbers because they assume they need 20 percent down and walk away from the search before they start. Don’t do that math in your head. Do it with a lender who works these programs weekly.
Loan Types That Actually Work Here
FHA loans are the workhorse for first-time buyers in Broward County. You can put down as little as 3.5 percent with a credit score of 580 or higher, and FHA loan limits for the Fort Lauderdale metro area are set high enough (typically in the $580,000-plus range as of 2026, adjusted annually) to cover nearly every starter home and townhome in Deerfield Beach. If your target property is a condo, confirm it’s FHA-approved before you fall in love with it. Not every complex is, especially older ones still working through post-Surfside reserve studies. A condo can be a great fit on paper and still fall through in underwriting if the building doesn’t meet FHA’s reserve funding requirements, so ask your agent to confirm FHA approval status before you write an offer, not after.
Conventional loans with 3 percent down (Fannie Mae HomeReady or Freddie Mac Home Possible) work well if your income qualifies and your credit is solid, generally 620 or above. These programs also allow gift funds for the down payment, which matters if family is helping. The tradeoff versus FHA is usually private mortgage insurance costs and slightly stricter debt-to-income requirements, so have your lender run both scenarios side by side rather than assuming one is automatically cheaper.
VA loans are zero-down and worth using if you or your spouse served. Deerfield Beach has plenty of VA-eligible single-family homes and townhomes, and there’s no reason to leave that benefit on the table. One thing veterans miss: VA loans have their own appraisal and minimum property requirements, which can be stricter on older homes with deferred maintenance, so an older Cresthaven home with an aging roof might need repairs completed before a VA appraisal clears it.
USDA loans don’t apply here. Deerfield Beach isn’t in a USDA-eligible rural area, so don’t waste time on that program for this location.
One thing that trips up first-time buyers: property insurance. Florida homeowners insurance has climbed hard over the past few years, and lenders qualify you including that payment. Get a real insurance quote before you fall for a house, not after you’re under contract. Flood zone matters too. Anything near the intracoastal or a canal in The Cove or Waterways likely needs flood insurance on top of standard coverage. A home two blocks apart in the same neighborhood can carry very different flood zone designations, so don’t assume the flood insurance quote on one house applies to the next one you look at.
Down Payment Assistance Programs Worth Knowing
Florida Hometown Heroes offers up to $35,000 in down payment and closing cost assistance for first-time buyers, and it’s not limited to first responders and teachers anymore. Most full-time Florida workers with a valid W-2 qualify if they’re under the income cap for the county. This is the single most useful program for a lot of buyers reading this, and it’s the one most agents outside of South Florida don’t know exists, so if you’re getting pre-approved with an out-of-state or online lender, specifically ask if they administer Hometown Heroes. Not all of them do.
Broward County SHIP (State Housing Initiatives Partnership) Homebuyer Purchase Assistance provides additional down payment and closing cost help for income-qualified buyers, often structured as a deferred second mortgage. It stacks with an FHA or conventional first mortgage, meaning you can layer Hometown Heroes and SHIP together in some cases, which is how buyers end up closing with close to nothing out of pocket beyond earnest money.
Employer and union programs are worth checking too. If you work for Broward County Public Schools, a hospital system, or a public safety agency, ask HR about homebuyer benefits before you assume you’re on your own for the down payment. Some of these are small, a few thousand dollars in closing cost credit, but combined with Hometown Heroes it adds up fast.
The reality is most first-time buyers in Deerfield Beach who use one of these programs get in with somewhere between 0 and 3 percent of their own cash, not the 20 percent people assume they need. Make wise decisions about which program fits your income and job, and talk to a lender who works these programs regularly, not one who’s never touched them. A lender who processes Hometown Heroes applications every week will move faster and catch eligibility issues earlier than one doing it for the first time on your file.
Starter Neighborhoods to Actually Target
Cresthaven and Kendall Green (west of Dixie Highway, north of Hillsboro): Older, established single-family blocks with real yards, mature trees, and prices that still make sense for a first house. No HOA in most of these older sections, which cuts your monthly cost but means you’re responsible for everything yourself. Lot sizes here tend to run larger than newer communities further west, which matters if you have kids or dogs and want actual yard space instead of a patch of turf between the house and the fence line.
Century Park: Townhome community with reasonable HOA dues covering exterior and common areas. A common landing spot for young families and first-time buyers who want low-maintenance living without condo fees eating the whole budget. It’s also close enough to Quiet Waters Park that weekend routines don’t require a car trip.
Waterways: Gated, with boat access for buyers who want the boating lifestyle without The Cove’s price tag. Condos and townhomes here are more affordable than the single-family canal homes closer to the beach. If having a boat or being near the water is a lifestyle non-negotiable but The Cove’s price point isn’t realistic, Waterways is the practical middle ground.
West Deerfield Beach near the Coconut Creek and Coral Springs line: This is where you’ll find the newer product and the most competitive pricing per square foot in the city. It’s also a fifteen-minute drive from I-95, so you’re trading beach proximity for value, which is the right trade for a lot of first-time buyers. If your daily life revolves more around work and school than weekend beach trips, this is usually where your money goes furthest.
Deer Creek: A golf course community with condos and villas that price below single-family homes, popular with buyers who want amenities (pool, golf, clubhouse) without single-family maintenance. It’s a good fit for a buyer who values community amenities over square footage.
If none of these fit and you’re open to new construction instead of resale, it’s worth widening the search. Miramar’s new construction pipeline has more active builders and inventory than Deerfield Beach right now, and communities like Solterra in Sunrise show what a Lennar-built starter community looks like at a similar price band. Neither is a substitute for buying in Deerfield Beach itself, but they’re useful comparisons if you’re deciding between “new and further out” versus “established and closer to the water.”
HOA and CDD Reality Check
Most of Deerfield Beach’s townhome and condo communities carry an HOA, and older single-family neighborhoods often don’t, which is a meaningful monthly cost difference to build into your budget. Deerfield Beach doesn’t carry the CDD (Community Development District) fees you’ll see in newer master-planned communities further west and north in Broward, because CDDs typically fund infrastructure for large ground-up developments, and Deerfield Beach is mostly built out. If you’re comparing Deerfield Beach to a newer community elsewhere in the county and see a CDD line item on a property disclosure, know what you’re looking at before you sign anything. Here’s a full breakdown of what a CDD fee actually is and how it works, worth reading regardless of where you end up buying.
For condos specifically, ask for the last two years of HOA financials and the most recent structural reserve study. Florida’s post-Surfside condo law requires buildings over three stories and 30 years old to complete milestone inspections and fund reserves properly, and that’s led to real special assessments in some older buildings. Don’t skip this step to save time. It’s the difference between a $300 monthly HOA fee and a $15,000 surprise assessment. If the HOA board minutes mention a pending assessment vote or a reserve study that flagged underfunding, that’s not a small detail buried in paperwork. That’s the number that decides whether the deal still makes sense at your budget. Ask your agent to request these documents on day one of your inspection period, not the week before closing.
Schools and Commute for Young Families
Deerfield Beach falls under Broward County Public Schools, with options including Deerfield Beach Elementary, Quiet Waters Elementary, Deerfield Beach Middle, and Deerfield Beach High School, plus several charter options in the area. If schools are a top priority and you’re cross-shopping, it’s worth looking at how a neighboring suburb stacks up. Plantation’s guide covers school zoning and commute trade-offs in a similarly established, inland Broward community, useful context even if you land in Deerfield Beach.
For commute, Deerfield Beach works both directions. I-95 and the Turnpike get you to Fort Lauderdale in 20 to 30 minutes depending on the exit, and Boca Raton and West Palm Beach are just as close going north. The Tri-Rail station in Deerfield Beach is a real option if you work near a station stop and want to skip 95 traffic. For a young family weighing a longer commute against a bigger yard, that flexibility to go either direction for work is worth more than it looks on paper. It means one spouse can work in Fort Lauderdale and the other in Boca without either one eating a brutal daily drive.
Step-by-Step: Your First-Time Buyer Roadmap
-
Get pre-approved before you look at a single listing. Talk to a lender about FHA, conventional 3 percent down, and whether you qualify for Hometown Heroes or Broward SHIP assistance. This determines your real number, not the number you assumed.
-
Pick your trade-off: proximity or price. Decide if you want beach proximity (higher price, The Cove, east of US-1) or value (west Deerfield Beach, Cresthaven, near the Coconut Creek line).
-
Decide condo, townhome, or single-family based on maintenance tolerance and HOA comfort. If you don’t want yard work or exterior repairs, a townhome or condo with a well-funded HOA makes sense. If you want no HOA and full control, target the older single-family stock.
-
Get an insurance quote before you go under contract. Flood zone, roof age, and wind mitigation all move the number, sometimes by hundreds of dollars a month.
-
For condos, pull the HOA financials and reserve study before your inspection period ends. This is non-negotiable in South Florida right now.
-
Use a local inspector who knows Broward-specific issues: older cast iron or polybutylene plumbing, roof age relative to insurance requirements, and AC unit age given the climate.
-
Close and budget for the first year realistically, including property tax reassessment (your tax bill often resets to the sale price the year after you close, higher than what the seller was paying under homestead exemption).
-
File for your own homestead exemption the January after you close. This is easy to forget in the excitement of moving in, but it caps how fast your tax bill can climb in future years and it’s free to file.
Comparing Deerfield Beach to Other First-Time Buyer Options
If you’re weighing multiple suburbs before committing, it helps to see how they stack up on paper. Pembroke Pines’ relocation guide covers a similar profile of buyer, family-oriented, commuter-friendly, but on the south side of Broward with a different price structure and more new construction turnover. Deerfield Beach’s advantage is being closer to the ocean and having more established, lower-maintenance older stock at a lower entry price than you’ll find in south Broward’s newer communities.
If your budget stretches further and new construction interests you more than resale, it’s worth understanding floor plan differences before you compare price per square foot across builders. Vineyards’ floor plan breakdown and Parkland Royale’s floor plan guide both walk through how layout, not just square footage, drives what a home actually feels like to live in, useful reading even if you end up buying resale in Deerfield Beach instead. The general rule holds across all of these markets: a smaller, well-laid-out home in an established neighborhood with low HOA fees often beats a larger new build with a higher HOA and a CDD assessment, once you run the real monthly numbers side by side.
The Bottom Line for First-Time Buyers
Deerfield Beach works for first-time buyers because it still has entry points under $350,000, real transit and highway access in both directions, and enough neighborhood variety that you can choose your trade-offs instead of settling. The reality is you don’t need 20 percent down and perfect credit to buy here. You need a lender who knows the Broward-specific assistance programs, a clear read on HOA and insurance costs before you commit, and a realistic sense of which neighborhood matches your budget and your life right now, not the one you’ll grow into in five years.
Start with pre-approval, get specific about your trade-offs between the beach and value, and don’t skip the HOA and insurance homework. That’s how you buy your first home in Deerfield Beach without a surprise six months in.
Watch: learn more
Go deeper with my South Florida Insider videos.

The Best Flex-Space Townhome in West Palm Beach: Pulte's Nautical Plan
Inside Everton's Latitude II Model: $458k New Homes In Palm Beach
The Best Flex-Space Townhome in West Palm Beach: Pulte's Nautical Plan
More articles you might like
Deerfield Beach, Florida: The Complete Guide (2026)
18 min read
First-Time Buyer's Guide to West Palm Beach: What to Know Before You Start
13 min read
First-Time Buyer in Pompano Beach: The Coastal Broward Option at a Better Price
18 min read
First-Time Buyer's Guide to Palm Beach Gardens: What's Actually Possible
14 min read
First-Time Buyer in Miami Beach: Is It Realistic and Where Do You Start?
13 min read