First-Time Buyer in Pompano Beach: The Coastal Broward Option at a Better Price
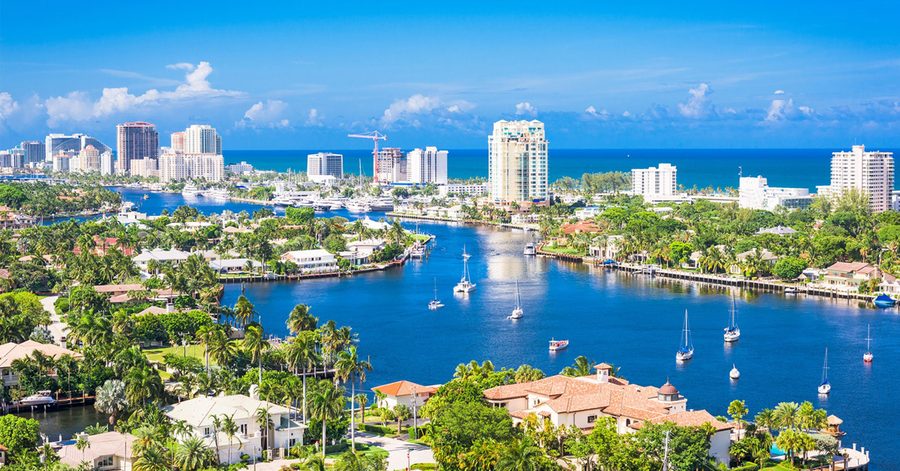
First-Time Buyer in Pompano Beach: The Coastal Broward Option at a Better Price
If you are a first-time buyer in Pompano Beach looking at what your money actually buys in coastal Broward, here is the short version: Fort Lauderdale priced most first-time buyers out years ago, and Pompano Beach is where that same buyer still has a real shot at owning something close to the water without stretching into a payment that does not work. It is not a discount version of Fort Lauderdale. It is an older, less polished, more affordable coastal city that is in the middle of redeveloping itself, and that gap between “still affordable” and “about to not be” is exactly why it matters right now.
This guide is for the buyer who has been watching Fort Lauderdale listings, doing the math, and coming up short. It walks through what entry-level actually looks like street by street, which property types make sense for a first purchase, what financing and insurance realities you need to plan for, and which pockets of Pompano are worth your time versus which ones are not, at least not yet.
Why Pompano Beach Became the First-Time Buyer Play
Fort Lauderdale’s entry-level housing stock has mostly been absorbed, renovated, or redeveloped. A basic 3-bedroom, CBS (concrete block) home inside Fort Lauderdale city limits, even in a modest neighborhood, now regularly clears $550,000 to $650,000. Condos under $300,000 in Fort Lauderdale proper are almost always older, smaller, further from the water, or carrying a milestone inspection and Structural Integrity Reserve Study (SIRS) assessment that changes the real cost of ownership.
Pompano Beach sits directly north of Fort Lauderdale, shares the same A1A corridor and Atlantic Ocean access, and still has meaningful inventory of older single-family homes and non-waterfront condos that have not been fully re-priced to match its neighbor. You are buying into the same metro, the same commute shed (I-95, Florida’s Turnpike, the Dixie Highway corridor, and Tri-Rail access), and the same beach, just a city or two north, where the price per square foot has not caught up yet.
That gap will not last indefinitely. Pompano’s downtown and beachfront corridors are already seeing serious capital move in. The Waldorf Astoria Residences Pompano Beach, the brand’s first standalone project of its kind, is rising along the beach. Salato Pompano Beach, a US Development project, is under construction with condos priced from roughly $2.0 million to over $5.2 million. That is luxury pricing you would expect in Fort Lauderdale or Miami, not what most people still associate with Pompano. When that kind of capital shows up on the beachfront, it does not stay contained to the beachfront. It pulls resale values up around it over a 5 to 10 year window, the same way Las Olas redevelopment pulled up prices in the Fort Lauderdale neighborhoods around it a decade ago. For a fuller picture of what is being built and what it costs, see our breakdown of new construction in Pompano Beach.
Buying the older, less exciting entry-level inventory now, before the redevelopment fully matures and before that luxury pricing trickles down into the rest of the city’s comps, is the actual strategy here. Not “it’s cheaper.” Cheaper is temporary. The strategy is timing.
What Entry-Level Actually Looks Like
Single-Family Homes
The realistic first-time buyer range for a single-family home in Pompano Beach in 2026 runs roughly $380,000 to $475,000 for a 3-bedroom, 2-bath CBS home built in the 1960s through 1980s, 1,200 to 1,600 square feet, on a standard 6,000 to 8,000 square foot lot. These are not new builds. They are original kitchens, original terrazzo or older tile, and roofs that may need attention within your first 5 to 10 years of ownership. That is the trade-off for the price.
You will find this stock concentrated in neighborhoods like Cresthaven, Collier City, McNab, and pockets of Highland Park. None of these are waterfront, and none of them are the polished, palm-lined streets you see in Pompano’s marketing photos. They are working, established neighborhoods with mixed renovation levels, house by house.
If you push your budget toward $500,000 to $575,000, you start unlocking better-renovated homes, larger lots, and neighborhoods like Palm Aire (inland, golf-course-adjacent, quieter) or homes a few blocks off the water in areas like Riverside Park.
To put a number on the actual trade-off: a buyer with a $450,000 budget in Fort Lauderdale is often looking at a 2-bedroom condo with an HOA and a milestone inspection hanging over it, or a very dated single-family home in a transitional block. That same $450,000 in Pompano can put you into a 3-bedroom CBS home with a fenced yard in Cresthaven or McNab, no HOA, and room to renovate the kitchen over time as your budget allows. That is the actual, practical difference this guide keeps pointing at.
Condos and Townhomes
This is where Pompano still offers a genuinely different value proposition than Fort Lauderdale. Non-waterfront, non-beachfront 2-bedroom, 2-bath condos in older buildings (built in the 1970s and 1980s, in complexes off Federal Highway, Cypress Road, or inland near Palm Aire) can be found from roughly $140,000 to $230,000. These are small, often 900 to 1,100 square feet, and they come with HOA fees in the $450 to $700 per month range that typically cover water, exterior maintenance, and (in many buildings now) a portion of the master insurance premium.
Townhomes run higher, generally $320,000 to $420,000 for a 2 or 3-bedroom unit built in the last 15 to 20 years, often in small HOA communities inland near Copans Road or west of Powerline Road. These carry lower HOA fees than condos (often $200 to $350 per month) because there is less shared structure, but they still carry an HOA, so read the budget and reserve study before you write an offer.
If proximity to the beach itself is the priority, older beachside condo buildings along or near A1A do exist in the $250,000 to $400,000 range for smaller, dated units, but these are almost always the buildings facing the steepest SIRS and insurance increases post-Surfside. More on that below.
A quick way to think about which of these three fits you: if you want no HOA, full control, and are comfortable with a project list, the older single-family home wins. If you want the lowest possible entry price and can accept a smaller footprint and shared decision-making through an association, the older condo wins. If you want something closer to new, low maintenance, and do not mind a slightly higher entry price, the townhome wins. Most first-time buyers we work with in Pompano end up choosing between the first and third option once they actually sit through a condo association’s meeting minutes.
The Condo Reality: SIRS, Milestone Inspections, and What It Means for You
Florida’s post-Surfside condo law changed the math on every condo building 3 stories or taller and over 30 years old (25 years old within 3 miles of the coast, which covers essentially all of Pompano’s beachside stock). Buildings now have to complete milestone structural inspections and fund a Structural Integrity Reserve Study, meaning associations can no longer waive reserves for major structural items like roofing, load-bearing walls, and waterproofing.
For a first-time buyer, this means two things in practice. First, ask for the most recent milestone inspection report and SIRS before you go under contract, not after. Second, budget for the possibility of a special assessment even in a building with a “low” HOA fee, because a low fee today sometimes means the building has been underfunding reserves and is about to correct that. A $180,000 condo with a $500 monthly HOA and a looming $15,000 special assessment is not actually cheaper than a $220,000 condo in a building that is already funded. Get the paperwork. This single step prevents more first-time buyer regret in older Broward condos than almost anything else.
Here is what that looks like in practice. Two buildings a half mile apart off Federal Highway can look nearly identical on paper, same decade built, same unit size, same view. One completed its milestone inspection two years ago, funded its SIRS on schedule, and carries a $620 monthly HOA. The other deferred its inspection as long as legally possible, is now facing a mandatory special assessment north of $20,000 per unit to cover roof and plumbing work, and its HOA is about to jump from $480 to $750 a month once the new reserve schedule kicks in. The second building will show up as “the better deal” in a basic MLS search sorted by price. It is not. Ask your agent to pull the last two years of board meeting minutes along with the SIRS, not just the SIRS itself, because the minutes tell you whether the board has been arguing about money.
Neighborhoods Worth a First-Time Buyer’s Look
Cresthaven and Collier City
Inland, working-class, established neighborhoods with the most consistent supply of sub-$450,000 single-family homes in the city. Mixed renovation quality. Good access to Copans Road and I-95. Not walkable to the beach, but a 10 to 15 minute drive. This is the neighborhood pairing where a first-time buyer’s dollar goes furthest, and it is also where you will see the widest range of condition on a single block, so a proper 4-point inspection matters more here than almost anywhere else on this list.
McNab and Highland Park
A step up in lot size and renovation level, still inland, still realistic for a first-time buyer with a $450,000 to $550,000 budget. Quieter streets, closer to Pompano’s newer retail corridor near Sample Road. This is a strong fit for a buyer who wants a little more breathing room, a two-car driveway, and proximity to grocery and everyday retail without paying for beach access they may not use every week anyway.
Palm Aire
Golf-course-adjacent, inland, quieter, and generally the best value for a buyer who wants a larger, better-maintained home and does not need to be near the water. More condos and villas here too, often 55-plus or age-restricted, so confirm occupancy rules if that matters to you. Palm Aire tends to attract buyers who are less focused on the beach lifestyle and more focused on a quiet, established community with mature landscaping and a slower pace, which is a legitimate and often overlooked first-time buyer profile in South Florida.
Riverside Park and Pockets Near the Beach
Smaller lots, older bungalows, a genuine walk-or-bike-to-the-beach lifestyle, but priced meaningfully higher than the inland neighborhoods above, often $550,000 and up for anything move-in ready. This is the neighborhood to watch if your budget stretches and beach proximity is non-negotiable. It is also the area most directly exposed to the redevelopment wave discussed above, meaning it carries both the highest current price and, arguably, the most upside if the Waldorf Astoria and Salato-level investment continues to spread inland from the beach over the next several years.
For a full breakdown of where each part of the city fits on the beach-to-inland, waterfront-to-avoid spectrum, our Pompano Beach neighborhoods guide goes block by block in more depth than we can cover here.
How Pompano Stacks Up Against Deerfield Beach and Lauderdale-by-the-Sea
If you are cross-shopping, it is worth knowing where Pompano sits relative to its immediate neighbors. Deerfield Beach, just north, runs a similar entry-level price band to Pompano for inland single-family homes, but has less inland inventory overall and a smaller stock of older condos, so you will see less selection at the low end. Lauderdale-by-the-Sea, just south, is a much smaller footprint and has almost no entry-level single-family inventory left. It functions more as a condo and vacation-rental market at this point, and pricing reflects that. Pompano, by comparison, still has enough volume of older single-family and non-waterfront condo stock that a first-time buyer actually has choices, not just whatever happens to be listed that month. That selection is part of what makes it the right target city for this specific kind of search right now.
Financing: What Actually Works for a First-Time Buyer Here
FHA loans (3.5% down) work on the vast majority of single-family homes in Pompano Beach and on condo buildings that carry FHA approval. Not every older condo building does. Some associations let approval lapse or never pursued it, which knocks out FHA buyers entirely and narrows your buyer pool if you ever sell. Ask your agent to confirm FHA and conventional condo approval status before you tour a unit seriously, not after you have already fallen for it.
Conventional loans with 5% to 10% down open up more inventory, including non-warrantable condo buildings, but expect a higher rate or added fees on some of those buildings due to Fannie Mae and Freddie Mac condo project restrictions that have tightened since 2023.
Florida first-time buyer down payment assistance programs (Florida Hometown Heroes, Florida Assist, and Broward County’s own SHIP programs) can apply here just like anywhere else in the county, and they are worth checking regardless of income level since some tiers reach further than people expect. Your lender should be running these numbers automatically, if they are not, ask.
It is also worth having a direct conversation with your lender about how condo approval status affects your rate, not just your eligibility. A conventional loan on a non-warrantable condo can carry a rate that is a quarter to a half point higher than the same loan on a warrantable one, and that difference compounds over a 30-year term into real money. On a $200,000 condo loan, a half point can mean an extra $60 to $70 a month, which is not dramatic on its own, but it is the kind of detail that should factor into whether you choose the FHA-approved building over the one that looks slightly nicer but lost its approval two years ago.
Budget for Insurance Before You Fall in Love with a House
Homeowners insurance in Broward County has climbed 30% to 80% since 2020, and that increase hits older, non-wind-mitigated homes hardest. A 1970s home with an original roof will cost meaningfully more to insure than a comparable home with a newer roof and hurricane-rated windows or shutters. Get a real insurance quote during your inspection period, not after closing. It has changed the affordability math on more than a few first-time buyer contracts in Broward over the past two years, and it is a much cheaper lesson to learn before closing than after.
This is also part of why newer construction, even at a higher purchase price, keeps pulling buyers away from older resale stock across Broward. Homes built to the current wind-mitigation and hurricane-impact codes qualify for real insurance discounts compared to legacy inventory, sometimes enough to offset a meaningful chunk of the higher mortgage payment. It will not make sense for every first-time buyer’s budget, but if you are deciding between an older Pompano resale and a smaller new build or newer condo a little further inland, run the full insurance-adjusted monthly number before you decide the resale is automatically the better deal.
Flood insurance is a separate line item and depends heavily on FEMA flood zone. Much of coastal Pompano sits in zones that require it regardless of whether your lender mandates it, so ask for the flood zone designation and a quote up front, especially on anything close to the Intracoastal or a finger canal.
Commute and Lifestyle Trade-Offs
Pompano Beach sits along I-95 and the Florida Turnpike, with a Tri-Rail and Brightline-adjacent station in the area giving car-free options toward Fort Lauderdale, Miami, and West Palm Beach for the right commuter. Federal Highway (US-1) and Dixie Highway run the length of the city and connect north to Deerfield Beach and south into Fort Lauderdale in about 15 to 20 minutes outside of peak traffic.
What you give up buying in Pompano instead of Fort Lauderdale is not access, it is polish. Downtown Pompano is still mid-transformation. Some retail corridors are dated. The beachfront itself has been redeveloped with newer hotels and the Pompano Pier area, but you will still see older strip malls and undeveloped lots a few blocks off the water in a way you mostly will not in Fort Lauderdale’s Las Olas corridor anymore. For a commuter working downtown Fort Lauderdale or Brickell, that 20 to 30 minute drive (longer during peak season traffic) is the real cost of the savings on the home itself, and it is worth actually driving the route at 8am on a weekday before you commit, not just estimating it from a map. If you want a full picture of what daily life here actually feels like, our Pompano Beach lifestyle guide covers the beach, pier, and restaurant scene in more detail.
Schools, Briefly
If you are a first-time buyer with kids or planning for them, school zoning should factor into which Pompano neighborhood you target, since assignment can shift meaningfully block to block in Broward County Public Schools. We cover this in full in our Pompano Beach schools guide, but the short version is: confirm zoned elementary, middle, and high school for the specific address before you write an offer, not the general area.
A Step-by-Step Framework for Buying Your First Home in Pompano Beach
- Get pre-approved and get a real insurance quote in the same week. Do not let insurance be an afterthought. It changes what you can actually afford.
- Decide house versus condo based on risk tolerance, not just price. A house gives you full control over your reserves and maintenance. A condo hands that control to an association, for better or worse.
- If you are looking at condos, request the milestone inspection report and SIRS before touring seriously. Pull the last two years of board meeting minutes alongside it. This is not optional in 2026.
- Pick 2 to 3 neighborhoods based on your actual daily life, not the listing photos. Cresthaven and Palm Aire live very differently than Riverside Park.
- Confirm FHA or conventional condo approval status early if you are financing with low down payment, and ask your lender how that status affects your actual rate.
- Check zoned schools for the exact address, not the ZIP code average.
- Get a 4-point inspection and roof age confirmed on any home built before 1990. This affects both insurability and negotiating leverage.
- Negotiate seller credits toward insurance or repairs rather than just price when the inspection turns something up. In this price range, sellers are often more flexible on credits than on the number itself.
- Drive your actual commute route at your actual commute time before you close. A map estimate and a Tuesday 8am reality are often two different numbers.
Where This Fits in the Bigger Broward Picture
Pompano Beach is not a secret anymore, but it is still underpriced relative to what is being built around it and what Fort Lauderdale now costs. Between the Waldorf Astoria Residences on the beach and multi-million dollar projects like Salato pulling in buyers who would otherwise be looking at Fort Lauderdale or Miami, the direction of this market is not really in question. The only real question for a first-time buyer is whether you get in on the entry-level side of that shift or wait until the entry-level side has closed. If you want the fuller relocation picture beyond just the first-time buyer angle, our Pompano Beach relocation guide and market update cover pricing trends, inventory, and where the opportunity is shifting next across the city.
The reality is that first-time buyers who wait for Pompano to feel “finished” before buying will pay Fort Lauderdale prices to do it. The ones who buy the honest, older inventory now, do the diligence on insurance and HOA health, and hold through the next redevelopment cycle are the ones who end up with real equity in a coastal Broward city instead of priced out of one entirely.
If you want to talk through what a specific budget actually gets you street by street in Pompano right now, that is a conversation worth having before you start touring. Reach out and we can walk through it together.
Watch: learn more
Go deeper with my South Florida Insider videos.

The Best Flex-Space Townhome in West Palm Beach: Pulte's Nautical Plan
Inside Everton's Latitude II Model: $458k New Homes In Palm Beach
The Best Flex-Space Townhome in West Palm Beach: Pulte's Nautical Plan
More articles you might like
Pompano Beach, Florida: The Complete Relocation Guide for 2026
20 min readLife in Pompano Beach: Beach, Pier, Restaurants, and What the City Is Becoming
17 min readPompano Beach Schools: What Families Need to Know (2026 Guide)
17 min readNew Construction in Pompano Beach: What Is Being Built and What It Costs (2026)
14 min readPompano Beach Investment Property: Why Investors Are Paying Attention in 2026
13 min read