Aventura Real Estate Market Update: Condo Prices and Trends in Mid-2026
Here is the revised, expanded post:
Aventura Real Estate Market Update: Condo Prices and Trends in Mid-2026
The short answer: Aventura’s condo market in mid-2026 isn’t one market, it’s two. Older buildings, mostly built before 1992, are working through Florida’s reserve funding mandate, and that’s showing up as softer prices and longer negotiations. Newer and ultra-luxury towers, the ones with funded reserves and completed structural inspections, are holding their value and in some cases still climbing. If you’re buying or selling in Aventura right now, which market you’re in matters more than the headline median price.
This guide breaks down what’s actually happening building by building, what’s driving it, and what you need to check before you write an offer. If you want the bigger picture on the city itself first, start with the Aventura, Florida: The Complete Guide for 2026.
Why Aventura’s Condo Market Split Into Two
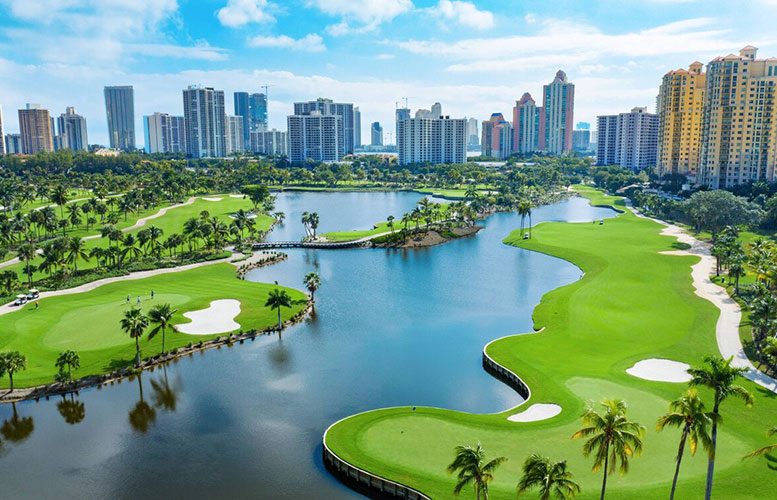
Aventura has always been a condo city. There’s very little single-family inventory inside city limits, most of what’s built here is mid-rise and high-rise condo product wrapped around the Intracoastal, Maule Lake, and the golf courses at Turnberry Isle. That building stock spans four decades, from 1980s towers to condos delivered in the last five years, and that age gap is now the single biggest factor in how a unit is priced.
I want to be direct about why this matters more in 2026 than it did even two years ago. Before the reserve law changes, an older building and a newer building competed mostly on location, view, and finish level. A buyer could look at two comparable two-bedrooms, one in a 1985 tower and one in a 2015 tower, and the price gap came down to amenities and condition. That’s not how it works anymore. Now the age of the building tells you almost as much about the real cost of ownership as the square footage does, because it tells you where that association sits on reserve funding, insurance renewal risk, and the likelihood of a special assessment landing on your desk in year two of ownership.
Pre-1992 Buildings and the Reserve Funding Reality
Florida passed reserve funding and milestone inspection requirements after the Surfside collapse in 2021 (SB 4-D and the follow-up SB 154). The short version: condo associations can no longer waive or underfund reserves for structural components like roofs, load-bearing walls, and windows, and buildings three stories or taller have to complete milestone structural inspections at 30 years old (25 years if within three miles of the coast, which covers most of Aventura).
By mid-2026, most of Aventura’s older buildings have gone through this. Some passed with modest dues increases. Others discovered deferred maintenance that requires either a special assessment or a loan the association takes out and bills back to owners monthly. I’ve seen assessments in older Aventura buildings run anywhere from $8,000 to $40,000+ per unit depending on the scope of work, and monthly HOA dues in some of these buildings have gone up 30 to 60 percent over the last two years.
Here’s what that actually looks like for a buyer. Say you’re touring a two-bedroom in one of the older towers off NE 34th Avenue, listed at $340,000, which sounds like a steal compared to a similar unit in a newer building three blocks away asking $520,000. If that older building just completed its SIRS and found $4.2 million in deferred concrete restoration and roof work across the property, and the association is financing it through a 10-year loan, your share of that could be a $22,000 special assessment payable over 60 months, on top of an HOA that just jumped from $650 to $890 a month. Run the real math on that and the $340,000 unit isn’t the deal it looked like on the listing sheet. This is exactly the trap I see relocating buyers fall into when they’re comparing price per square foot across buildings without pulling the paperwork first.
This is the single biggest reason you’ll see a two-bedroom in an older Aventura building listed for what looks like a great price. The purchase price isn’t the real cost. Ask for the last two years of board meeting minutes, the most recent reserve study or structural integrity reserve study (SIRS), and the milestone inspection report before you get attached to a unit. If the seller or listing agent can’t produce these quickly, that’s information too. A listing agent who stalls on producing board minutes is telling you something, even if they never say it out loud.
Newer and Luxury Towers Holding Value
Buildings delivered in the last 10 to 15 years, like Marina Palms Yacht Club & Residences on the Intracoastal, and the Williams Island towers, went through the reserve law changes with far less disruption because they were already funding closer to what the law now requires. Their HOA dues have gone up too, insurance costs hit every building in South Florida, but the increases have been in the range of 10 to 20 percent rather than the dramatic jumps seen in older stock.
That stability is showing up in price behavior. These buildings aren’t seeing the discounting that older towers are, they’re seeing longer days on market and buyers negotiating harder, but list-to-sale ratios have stayed closer to 95 to 97 percent instead of the 88 to 92 percent I’m seeing on some older listings that have sat for six-plus months.
What’s worth understanding is why buyers are willing to pay that premium even in a market where they clearly have negotiating leverage elsewhere. It comes down to predictability. A buyer looking at a Williams Island unit knows the reserve study is current, the insurance renewal came in at a manageable increase, and there’s no pending vote on a special assessment hanging over the next annual meeting. That certainty is worth real money to buyers who have already been burned, or who’ve heard enough horror stories from friends in older Miami-Dade buildings to want no part of that risk.
Price Bands by Building Type and Neighborhood in Mid-2026
Here’s roughly where things stand as of mid-2026. These are ranges, not quotes, always verify against active comps for the specific building, but this gives you the real shape of the market.
Entry-Level: Older 1980s-90s Buildings
Buildings like those around the Aventura Boulevard and NE 34th Avenue corridor, older Hamptons-era towers, and smaller boutique buildings from that first wave of Aventura development are where you’ll find the entry point. A one-bedroom runs roughly $220,000 to $320,000, a two-bedroom $300,000 to $430,000. That’s before you factor in whatever the reserve situation looks like. This is exactly the segment where the special assessment question matters most, and it’s also the segment I walk relocating and first-time buyers through most carefully. If you’re evaluating this tier, read First-Time Buyer in Aventura: What the Entry Level Looks Like before you start touring.
A practical note on this tier: don’t let the low entry price convince you to skip the diligence steps I’m laying out later in this guide. I’ve had buyers in this price band walk away from three units before finding one with a clean reserve study and no pending assessment vote. That’s not bad luck, that’s what the current market looks like at this price point. Expect to kiss a few frogs before you find the right building.
Mid-Tier: Renovated and 2000s-Era Buildings
Buildings from the early-to-mid 2000s, and older buildings that have completed renovations and fully funded their reserves, sit in the $450,000 to $850,000 range for one and two-bedroom units, with larger three-bedroom layouts pushing toward $1M. This tier tends to have the most predictable HOA situation because most of these associations went through their major capital work in the 2010s, before the current insurance and reserve pressure hit.
This is often the sweet spot for move-up buyers and relocating families who want space, a reasonably current building, and a defensible HOA number without paying the ultra-luxury premium. You’re typically looking at buildings with a renovated lobby, updated common areas, and a pool deck that’s been redone in the last decade. The tradeoff is usually amenity depth. You won’t get the full-service concierge and marina access of the top tier, but you also won’t be underwriting a surprise assessment on a building that’s still working through 1990s-era plumbing and electrical.
Ultra-Luxury Waterfront: Williams Island, Porto Vita, Marina Palms, Turnberry Isle
This is where Aventura’s reputation as a waterfront luxury market really shows. Units in Williams Island’s guard-gated towers, Porto Vita’s twin towers on the Intracoastal, and Marina Palms with its private marina and yacht basin, typically start around $900,000 for a smaller unit and run well past $3M for larger, higher-floor, and penthouse product. HOA dues here reflect the amenity level, concierge, valet, marina access, full-service spa and fitness, and can run $1.20 to $1.75 per square foot per month. For a full breakdown of what waterfront living actually costs and looks like day to day, see Waterfront Living in Aventura: Intracoastal Views and Marina Access, and for a building-by-building read on which towers are worth the premium, Aventura Condo Guide: Which Buildings Are Worth Buying and Why (2026) goes deeper than price alone.
Buyers in this tier are underwriting differently than buyers in the entry-level segment. A $1.6 million buyer at Williams Island isn’t comparing HOA dues line by line the way a $280,000 buyer off NE 34th Avenue has to, because the math works differently when you’re already committed to a lifestyle purchase. What they are checking, and checking carefully, is whether the association’s reserve funding matches what they were told at the listing appointment, because at this price point a misrepresentation isn’t a rounding error, it’s a six-figure mistake.
What’s Actually Driving Demand Right Now
Cash Buyers and International Money
Aventura has always drawn a heavy cash-buyer base, a lot of it from Latin America and Canada, and that hasn’t changed in 2026. Roughly half of condo closings in this price range are still cash. That matters for you as a buyer because it means financed offers need to be clean and fast to compete, and it matters for sellers because it means the buyer pool isn’t as rate-sensitive as it is in other parts of the country.
For financed buyers, that means having your pre-approval, proof of funds for the down payment, and a lender who already understands Florida condo warrantability lined up before you tour, not after you find a unit you like. Cash offers still routinely win when a seller has two comparable offers on the table, even when the financed offer is close on price, simply because the seller knows there’s no financing contingency risk hanging over the closing date.
Insurance and HOA Costs Are the Real Story
If you take one thing from this update, take this: insurance and HOA cost, not interest rates, is what’s actually moving Aventura condo pricing in 2026. Buyers are running the true carrying cost, purchase price plus HOA plus property insurance plus any assessment, before they make an offer, and that math is now killing deals that would have closed easily three years ago on price alone. If you’re underwriting a purchase as an investment rather than a home, the full breakdown of what the numbers actually look like right now is worth reading before you run your own projections: Aventura Condo Investment: What the Numbers Look Like in 2026.
I’ll give you a real comparison to make this concrete. Two buyers, both looking at $500,000 two-bedrooms. Buyer A is looking at a unit in a newer building with a $780 monthly HOA and a $2,900 annual insurance quote. Buyer B is looking at a comparable unit in an older building with a $1,150 monthly HOA (post-assessment increase) and a $4,600 annual insurance quote, because the older structure carries a higher risk profile with the carrier. Over five years, Buyer B is paying roughly $28,000 more in carrying costs alone, before accounting for any special assessment. That’s the conversation buyers need to be having before they fixate on the sale price.
Interest Rates and Financing
Rates have come down some from their 2023-2024 peak but they’re still elevated relative to the 2020-2021 era, and condo financing in Florida carries its own complications right now. Lenders are pulling reserve studies and requiring associations to certify they’re not underfunded before approving loans on a building, sometimes called warrantability review. Some older Aventura buildings currently don’t qualify for conventional financing until they clear that review, which pushes those units toward the cash buyer pool and can suppress pricing further. Ask your lender to check a building’s warrantable status before you fall in love with a unit.
This is worth repeating because it trips up buyers constantly. You can have a great credit score, a strong down payment, and a fully approved pre-qualification, and still get denied on a specific unit because the building itself doesn’t meet lender guidelines. That’s not a you problem, it’s a building problem, and it’s becoming more common in Aventura’s older stock as reserve requirements tighten. Some buyers are having to switch from conventional financing to portfolio lenders or local credit unions that underwrite these buildings differently, often at a slightly higher rate.
Days on Market, Inventory, and Negotiating Room
Inventory in Aventura has loosened up compared to the tight 2021-2022 market. You’re seeing more listings sit 60, 90, even 150+ days, especially in the older buildings still working through special assessment disclosures or dues increases. That gives buyers real negotiating room on those units, sellers are more willing to come off list price, credit toward closing costs, or cover a portion of an upcoming assessment to get a deal done.
On the newer, well-capitalized buildings, inventory is thinner and well-priced units are still moving in 30 to 60 days. If you find a unit in a building like Marina Palms or Williams Island priced correctly, don’t expect to negotiate it the way you would in an older tower down the street. Two buildings half a mile apart can be in completely different markets right now, and that’s the reality every Aventura buyer needs to understand before they anchor to a number they saw on Zillow.
For sellers in the older-building category, this market rewards getting ahead of the disclosure conversation rather than hoping it doesn’t come up. If your building has a completed SIRS and a manageable path forward, put that in the listing remarks and have it ready as a document packet before the first showing. Buyers and their agents are asking for it anyway, and a seller who hands it over immediately looks a lot more credible than one who makes a buyer chase it down after an accepted offer. I’ve seen deals fall apart during due diligence purely because the paperwork took two weeks to produce and the buyer’s confidence eroded in the meantime.
New Construction vs Resale in Aventura
Aventura is largely built out, so there isn’t a wave of new towers breaking ground the way you see in Sunny Isles Beach or downtown Miami. What is coming tends to be smaller-scale, higher-end product replacing older sites, and it prices at a real premium to resale, often $1,200 to $2,000+ per square foot depending on location and finish level. For buyers who want the predictability of new construction (current Florida Building Code, no deferred maintenance, reserves funded from day one) it’s worth understanding exactly what’s in the pipeline and what it actually costs before you compare it against resale. That full rundown is in New Construction Condos in Aventura: What Is Coming and What It Costs.
The honest tradeoff: new construction gets you predictable carrying costs and current-code storm protection, but you’re paying a real premium per square foot and you’re choosing from a much smaller inventory pool than resale offers. Most buyers end up comparing a handful of new units against dozens of resale options, and the right call depends on your time horizon and how much you value predictability over price.
If you’re weighing Aventura against neighboring markets for this same reason, it’s worth knowing that Sunny Isles Beach and Hallandale Beach both have considerably more new construction activity right now, simply because there’s more developable land along those stretches of coastline. That doesn’t make Aventura the wrong choice, its location between the Turnberry golf courses, Aventura Mall, and the Intracoastal is hard to replicate, but if new construction with a lower per-square-foot number is the priority over location, those neighboring markets deserve a look before you commit to Aventura resale.
What Buyers Should Actually Do in This Market
-
Get the reserve study and milestone inspection report before you write an offer, not after. If the building hasn’t completed its milestone inspection yet, find out when it’s scheduled and what the association is projecting it will cost.
-
Calculate true monthly cost, not just HOA dues. Add HOA, estimated property insurance (get a real quote, don’t guess), property tax, and any known or pending assessment divided over 12 months. Compare that number across buildings, not just the sale price.
-
Check the building’s financing status with your lender before you tour. A non-warrantable building limits your buyer pool if you resell later and may mean a higher rate or larger down payment now.
-
Use the softer market on older buildings to negotiate, but only after you’ve confirmed the reserve situation. A discount on the purchase price doesn’t help you if it’s smaller than the assessment you didn’t know was coming.
-
On newer, fully-funded buildings, move quickly on well-priced units. These aren’t sitting the way older inventory is.
-
Read the last two years of board meeting minutes, not just the current reserve study. Minutes often flag a coming vote or a discussion about a special assessment months before it becomes official. That gives you an early warning the reserve study alone won’t show.
-
Ask about pending or recent litigation involving the association. Construction defect suits, insurance disputes, and assessment challenges are all things a good listing agent should disclose, but you should ask directly and get it in writing.
If you’re relocating and trying to figure out where Aventura fits against other North Miami-Dade options, or you want the full picture of schools, lifestyle, and neighborhoods before you narrow down a building, the Moving to Aventura: Miami-Dade’s Upscale Condo City on the Water guide and Life in Aventura: Mall, Marina, Waterways, and What Daily Life Really Looks Like cover that ground. And if you’ve got school-age kids, the reserve and assessment conversation matters just as much as it does anywhere else, but you’ll also want the district picture, which is covered in Aventura Schools: What Families Need to Know.
The Bottom Line for Mid-2026
Aventura isn’t a single market you can summarize with one median price, and anyone who tells you it is hasn’t looked at an individual building’s financials lately. Older buildings are repricing in real time as reserve funding and insurance costs get fully disclosed, which creates real opportunity if you do the diligence and real risk if you don’t. Newer and luxury towers are holding their ground because they built the cushion in years ago.
Know which market you’re actually shopping in before you compare prices across listings. That one distinction, older versus newer, underfunded versus fully reserved, will save you more money than any negotiating tactic. If you’re serious about buying or selling in Aventura this year, do the paperwork work up front. The buyers who are winning right now aren’t the ones moving fastest, they’re the ones asking for the reserve study on day one.
More articles you might like
Aventura vs. Boca Raton: Condo Life vs. Suburban House, Which Fits Your Budget?
20 min readAventura, Florida: The Complete Guide for 2026
19 min readFirst-Time Buyer in Aventura: What the Entry Level Looks Like
13 min readAventura Schools: What Families Need to Know (2026 Guide)
13 min readNew Construction Condos in Aventura: What Is Coming and What It Costs
14 min read