Buyer's Guide to Briny Breezes, FL: What to Know Before You Purchase

Buyer’s Guide to Briny Breezes, FL: What to Know Before You Purchase
If you’re building a buyer’s guide to Briny Breezes, FL, what to know before you purchase starts with one fact most people miss until they’re already under contract: you’re not buying a house in the way you buy a house anywhere else in Palm Beach County. You’re buying a share in a corporation. That single detail changes financing, resale, approval, and even how you think about “ownership.” Everything else, the price ranges, the housing stock, the due diligence, flows from that fact. This guide walks through it in full, so you go into an offer with your eyes open instead of finding out the hard way at closing.
What Makes Briny Breezes Different From Every Other Florida Purchase
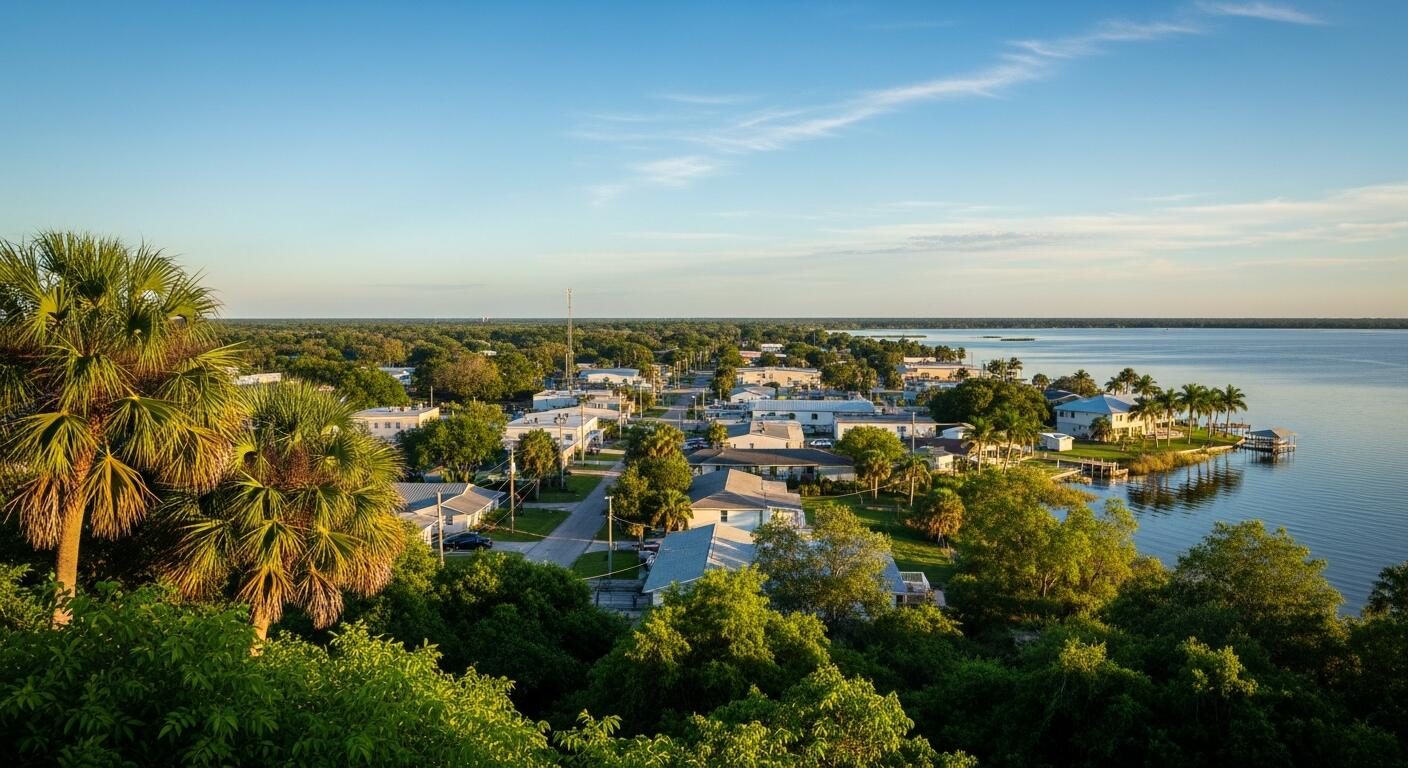
Briny Breezes is a tiny, incorporated town on a barrier island in southern Palm Beach County, sandwiched between Ocean Ridge to the north and Gulf Stream to the south, with the Atlantic Ocean on one side and the Intracoastal Waterway on the other. It covers roughly 43 acres, making it one of the smallest towns in Florida by land area, and it’s home to fewer than 600 residents on a full-time basis, with the population swelling seasonally as snowbirds return each winter.
What sets it apart isn’t the size. It’s the ownership structure. Briny Breezes, Inc. is a Florida cooperative corporation that owns the entire town, every lot, every road, every inch of common area. Residents don’t buy land or a deeded home. They buy shares of stock in the corporation, and that stock ownership comes with a proprietary lease on a specific home site. You own the mobile home, manufactured home, or cottage sitting on the lot, but the ground underneath it belongs to the co-op, not to you individually.
This is the single most important thing to understand before you purchase, and it’s why we’re rewriting this guide from the ground up instead of treating Briny Breezes like any other Palm Beach County suburb. For the pricing trends and market data side of this, pair this guide with our Briny Breezes, FL Real Estate Market 2026 breakdown, and for a candid take on lifestyle fit, read Is Briny Breezes a Good Place to Live? Honest 2026 Review.
Where Briny Breezes Sits on the Map
Briny Breezes runs along State Road A1A, directly between Ocean Ridge and Gulf Stream, with Boynton Beach just to the north and Delray Beach a short drive south. It shares a 33435 zip code with Boynton Beach, and most day-to-day errands, groceries, hardware, medical care, happen in Boynton Beach or Delray Beach rather than inside the town itself, since Briny Breezes has no real commercial district of its own.
The location is genuinely rare. You’re on a barrier island with ocean access on one side and Intracoastal frontage on the other, in a county where oceanfront land routinely commands seven figures per lot elsewhere. That’s part of what makes the co-op structure so notable: it’s the mechanism that has kept this stretch of oceanfront affordable relative to everything around it, because you’re not purchasing the underlying real property.
The Co-op Structure: What You’re Actually Buying
Share Ownership vs. Fee Simple
In a normal Florida purchase, you get a warranty deed and you own real property in fee simple. In Briny Breezes, you’re issued a stock certificate representing your shares in Briny Breezes, Inc., and a proprietary lease that assigns you the exclusive right to occupy a specific lot. The number of shares tied to a given lot generally correlates with the lot’s size and location, oceanside lots and larger sites typically carry more shares than smaller interior lots.
This isn’t a minor technicality. It affects your title work, your closing process, your ability to finance, your property tax treatment, and how you eventually sell. Any attorney or title company you use needs specific experience with Florida stock cooperatives, not just standard residential closings. Ask this question directly before you hire anyone: “Have you closed a Briny Breezes transaction before?” If the answer is no, keep calling until you find someone who has.
The Approval Process
Because you’re buying into a corporation, the corporation typically has a say in who buys. Co-op boards commonly require prospective buyers to submit an application, sometimes including financial disclosures and an interview or board approval, before a sale can close. This is standard practice for cooperative housing nationally, and Briny Breezes follows the same general model. Build this into your timeline. A sale that would close in 30 days on a normal single-family home can take longer here simply because of the approval step, and if the board declines to approve a buyer, the deal doesn’t happen no matter what the contract says.
Get the corporation’s current bylaws, rules, and application requirements from the listing agent or the co-op office before you write an offer, not after. You want to know the approval timeline, what documentation is required, and whether there’s any waiting list or seasonal restriction on when new owners can take occupancy.
Monthly Assessments and What They Cover
Instead of a traditional HOA fee, Briny Breezes owners pay a monthly co-op assessment. That fee funds the shared infrastructure the corporation maintains: roads, common areas, the clubhouse, beach access points, and general upkeep of the property the corporation owns. Because the co-op also carries its own insurance and reserve obligations on shared infrastructure, ask specifically about the corporation’s reserve fund status and whether any special assessment is pending or has occurred recently. A barrier island community with an aging shared seawall, aging docks, or beach erosion exposure can face large infrastructure costs, and those get passed to shareholders. This is a due diligence item, not a footnote.
What the Money Buys: Price Ranges and Housing Stock
Oceanside vs. Intracoastal Side
Pricing in Briny Breezes varies by which side of A1A a lot sits on and by proximity to the water. Oceanside lots, and units with unobstructed ocean or beach access, generally command a premium over interior or Intracoastal-side lots. Because pricing here moves differently than the broader Palm Beach County MLS (fewer transactions, unique financing, co-op approval affecting who can even bid), treat any number you see online as a starting point, not gospel. Pull current active listings and recently closed co-op sales before you set expectations, and lean on an agent who has actually worked a transaction here. The Briny Breezes market update tracks these trends in more depth if you want the current pricing picture before you start touring.
Home Types and Sizes
The housing stock is almost entirely mobile homes, manufactured homes, and park-model style cottages, with a mix of vintages, many dating back decades, alongside newer units that owners have brought in to replace older ones on the same leased lot. Square footage tends to be modest, often in the range of a few hundred to a bit over a thousand square feet, reflecting the manufactured-home format rather than site-built suburban construction. Don’t walk in expecting anything resembling a typical 2,000-plus square foot single-family home. This is compact, efficient, low-maintenance living by design, and that’s exactly what draws a certain kind of buyer to it.
If your priority is a true new-construction single-family home with modern floor plans and builder warranties, Briny Breezes isn’t that product, and you should look instead at a growing new-construction market like Agave Boca in Boca Raton, or compare a planned new-build community such as Westlake’s real estate market and its own buyer’s guide against what Briny Breezes actually offers.
Financing Reality: Why Most Purchases Are Cash
This is where a lot of buyers get tripped up. Because you’re purchasing a cooperative share and a proprietary lease rather than a deeded home, conventional 30-year mortgages are difficult to find. Most Fannie Mae and Freddie Mac conforming loan programs are built around fee-simple or standard condo ownership, and a stock cooperative with a corporate-owned underlying lot doesn’t fit that box cleanly. The practical result: the majority of Briny Breezes purchases close in cash.
There are sometimes portfolio lenders, local credit unions, or specialty co-op loan products willing to finance a share purchase, but availability changes over time and isn’t guaranteed from one lender to the next. If financing matters to your plan, get pre-qualification confirmation in writing from a lender who has specifically financed a Briny Breezes co-op share before you get attached to a listing. Don’t assume your regular mortgage broker can make it work just because they’ve closed deals elsewhere in Palm Beach County.
Budget for the fact that a cash requirement changes your negotiating posture too. Sellers here are often more comfortable moving quickly with a proven cash buyer than waiting on a financing contingency that might not clear underwriting at all.
New Construction and Redevelopment: What’s Actually Allowed
Briny Breezes is fully built out. There’s no raw land inventory and no active subdivision bringing new homesites to market. What passes for “new construction” here is an owner removing an aging unit and placing a new manufactured or modular home on the same leased lot, and that process runs through corporation approval on size, setbacks, and design before it happens. There is no builder sales office, no model home tour, and no incentive package the way there is in a true new-construction community.
It’s also worth knowing the town’s history here, because it shapes how residents think about long-term redevelopment risk. In the mid-2000s, Briny Breezes shareholders came close to approving a sale of the entire town to a developer for a large-scale luxury redevelopment, a deal that ultimately fell apart. That episode still shapes conversations among longtime shareholders about the corporation’s future and any prospect of a future buyout offer. If you’re purchasing with a long time horizon, it’s a reasonable question to ask current board members or longtime owners directly: has anything like that resurfaced, and how did the membership vote last time.
Who Briny Breezes Is (and Isn’t) Right For
Briny Breezes works well for retirees and snowbirds who want genuine oceanfront access, a small tight-knit community, and a lower buy-in than deeded oceanfront property anywhere else in the county, and who are comfortable with cash purchase, co-op governance, and a modest manufactured-home footprint. It works less well for a full-time working family that wants space, top-rated zoned schools nearby as a daily commute consideration, or a conventional mortgage. If that’s your profile, you’ll likely be happier looking at a family-oriented Palm Beach County suburb instead; our roundup of the best Palm Beach County suburbs for families relocating in 2026 is a better starting point for that search.
It also isn’t the right fit for anyone who wants a traditional resale exit process. Selling a co-op share means finding a buyer willing to go through the same approval process you did, which narrows your buyer pool compared to a standard deeded listing.
Due Diligence Checklist Before You Make an Offer
Work through this list with your agent and a real estate attorney experienced in Florida cooperatives before you sign anything:
- Confirm the share count and lease terms tied to the specific lot, and get a copy of the proprietary lease itself, not just a summary.
- Request the corporation’s bylaws and buyer application requirements, including any board interview or financial disclosure step, and build the approval timeline into your contract.
- Ask for the co-op’s current financials, including reserve fund balances, any pending or recent special assessments, and outstanding debt held by the corporation.
- Get the monthly assessment amount in writing along with what it covers and its recent increase history.
- Confirm financing availability in writing from a lender who has actually closed a Briny Breezes share purchase, or budget to pay cash.
- Have the home inspected the same as you would any manufactured or mobile home, checking age, tie-downs, roof condition, plumbing, and electrical, since ages vary widely across the community.
- Check flood zone designation and elevation for the specific lot, since barrier island placement means flood risk varies by exact location relative to the ocean and Intracoastal.
- Ask about rental and leasing restrictions. Many cooperatives restrict or prohibit short-term and even long-term rentals, which matters if you’re considering this as an income property rather than a primary or seasonal residence.
- Ask directly about redevelopment history and sentiment, given the town’s past near-sale, so you understand where the membership currently stands.
- Clarify what happens to your share and lease upon resale or in an estate situation, since this differs from a standard deeded property’s title transfer.
Insurance, Flood Zones, and Barrier Island Realities
Any purchase on this stretch of A1A comes with barrier island insurance realities: windstorm coverage, flood insurance, and often higher premiums than you’d see on the mainland a few miles west. Get an insurance quote before you’re under contract, not after, because a surprise premium can change your monthly cost picture significantly. Ask specifically whether the property has ever had flood claims, what the elevation certificate shows, and whether the co-op carries any master insurance policy on shared infrastructure that affects your individual coverage needs. Seawalls, docks, and shared beach access points on the Intracoastal side are shared-cost items when they need repair, so factor that into your assessment questions above.
How Briny Breezes Compares to Nearby Palm Beach County Towns
Compared to its immediate neighbors, Ocean Ridge and Gulf Stream, both of which are deeded, fee-simple single-family markets with prices running dramatically higher, Briny Breezes is the affordability outlier on this stretch of oceanfront, and the co-op structure is the reason why. If you’re cross-shopping the county broadly, it’s worth reading how nearby markets stack up in West Palm Beach vs. Palm Beach Gardens or Jupiter vs. Palm Beach Gardens to see what a conventional deeded purchase buys you elsewhere in the county at a comparable price point, and how differently that money performs once you’re not paying for direct oceanfront proximity.
The Bottom Line
Briny Breezes rewards buyers who do the homework and understand exactly what they’re purchasing: a cooperative share, a proprietary lease, cash-heavy financing, and a small, seasonal, tight-knit community on genuinely rare oceanfront ground. It punishes buyers who treat it like a normal Palm Beach County listing and skip the co-op-specific due diligence. Get the bylaws, get the financials, get a lender who’s done this before, get an attorney who’s closed here, and go in with realistic expectations on square footage and resale process. Do that, and Briny Breezes can be one of the most distinctive, affordable oceanfront opportunities left in South Florida.
Watch: learn more
Go deeper with my South Florida Insider videos.
Solterra: Everything You Need to Know Before You Visit
Solterra: Everything You Need to Know Before You Visit
More articles you might like
Briny Breezes, FL Real Estate Market 2026: Prices, Trends & What Buyers Should Expect
17 min readIs Briny Breezes a Good Place to Live? Honest 2026 Review
13 min read
Buyer's Guide to Westlake, FL: What to Know Before You Purchase
13 min read
Buyer's Guide to Tequesta, FL: What to Know Before You Purchase
18 min read
Buyer's Guide to South Palm Beach, FL: What to Know Before You Purchase
19 min read